Ask retirees what they fear most and the answer is rarely dying — it is outliving their money. Every paycheck they ever earned had one thing in common: it arrived on schedule, month after month, no matter what the stock market did. Then retirement begins, the paychecks stop, and a lifetime of savings is suddenly expected to do a job it was never designed for.
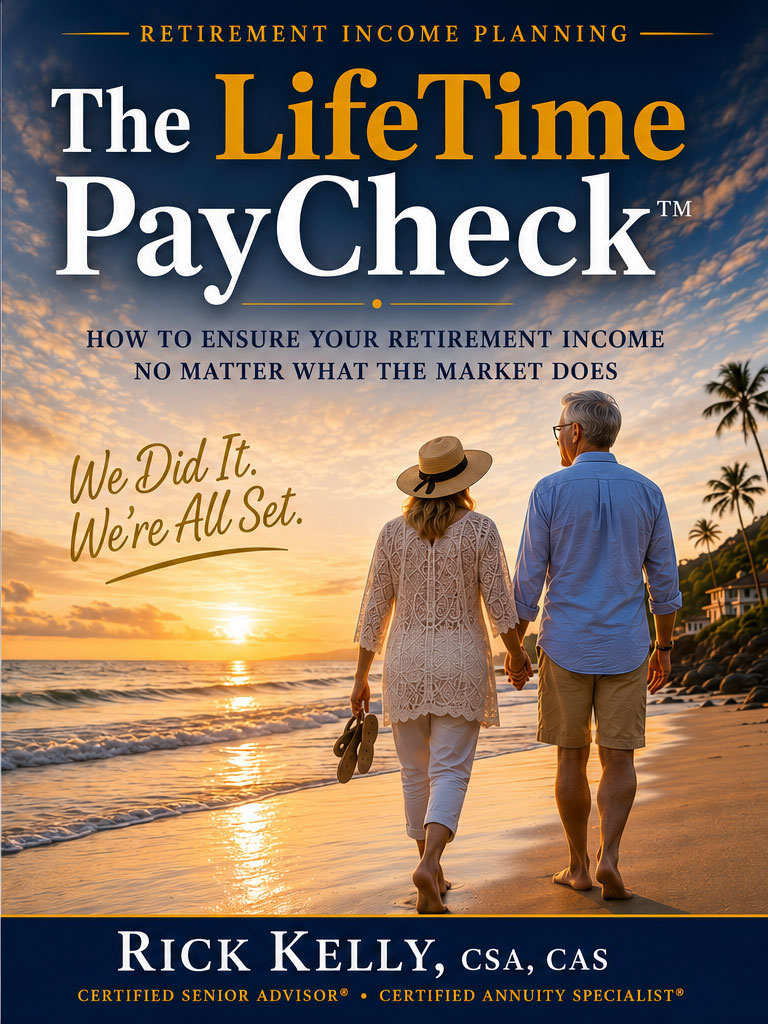
There is a solution, and it is older and simpler than most people realize: convert a portion of your savings into a guaranteed lifetime paycheck — income that is contractually guaranteed to arrive every month for as long as you live, and for as long as your spouse lives. Rick Kelly calls it The LifeTime PayCheck, and it is the subject of his book of the same name, available free at thelifetimepaycheck.com.
This is not speculation, and it is not a product pitch. It is the same principle behind the traditional pensions and Social Security that made previous generations of retirements secure — applied deliberately to your own savings.
What is a guaranteed lifetime paycheck?
A guaranteed lifetime paycheck is monthly income created from a portion of your retirement savings that is contractually guaranteed to continue for the rest of your life — regardless of how long you live, and regardless of what happens in the markets. It is, in effect, a personal pension you create for yourself.
The guarantee does not come from market performance, projections, or hope. It comes from a contract with an insurance company, and it is backed by that company's claims-paying ability — which is exactly why company strength and contract terms matter so much, and why education comes before any decision. Once the right contract is in place, your essential expenses are covered by income designed to continue for life.
Why savings alone cannot do the job
The traditional approach — keep everything invested and withdraw four percent a year — asks your portfolio to survive two unknowns at once: how long you will live and what markets will do along the way. A deep downturn early in retirement, combined with ongoing withdrawals, can permanently damage a plan that looked healthy on paper.
Longevity makes the problem harder, not easier. For a healthy couple at 65, there is a meaningful chance at least one spouse lives past 90. That can mean thirty years of withdrawals through every bear market, recession, and inflation cycle along the way. A guaranteed lifetime paycheck removes both unknowns from the part of your plan that matters most: the income that pays for your life.
The certainty split: guarantee the essentials, invest the rest
Creating a lifetime paycheck does not mean converting everything. The approach Rick teaches is a simple division of labor for your money.
- Add up your essential monthly expenses — housing, food, healthcare, utilities, insurance.
- Subtract guaranteed income you already have, such as Social Security and any pension.
- Cover the gap with a guaranteed lifetime paycheck created from a portion of your savings.
- Leave the rest invested for growth, inflation protection, travel, and legacy — free to ride out market cycles, because your essentials no longer depend on it.
Why education must come before any decision
Not every income product deserves your money. Contracts differ enormously in their guarantees, costs, spousal protections, and the financial strength of the company standing behind them. Choosing well is a matter of education first — which is exactly why Rick wrote The LifeTime PayCheck and makes it free to every reader at thelifetimepaycheck.com.
Rick Kelly is a Certified Senior Advisor (CSA), a Certified Annuity Specialist (CAS), and a verified advisor on safemoney.com — America's nationally recognized retirement education platform, which vets and lists independent advisors held to strict education-first standards. That combination of credentials and independence means the guidance starts with your situation, never with a product.
How to get started
The first step costs nothing: read the book. The LifeTime PayCheck explains, in plain language, how a guaranteed lifetime paycheck works, who it is right for, and how to evaluate the options — so that when you sit down with any advisor, you understand exactly what is being proposed and why.
Download your free copy at thelifetimepaycheck.com. If you would rather talk it through, every consultation with Rick is free, educational, and carries no obligation of any kind.
Frequently Asked Questions
What is a guaranteed lifetime paycheck?
It is monthly retirement income, created from a portion of your savings, that is contractually guaranteed to continue for as long as you live — no matter how long that is and no matter what the markets do. Rick Kelly calls it The LifeTime PayCheck; it works like a personal pension.
How do I create retirement income I can't outlive?
You convert a portion of your savings into a contractually guaranteed income stream through an insurance company — enough to cover the gap between your essential expenses and existing guaranteed income like Social Security. The rest of your savings stays invested for growth. Guarantees are backed by the claims-paying ability of the issuing insurer, which is why choosing a strong company and the right contract matters.
Where can I get The LifeTime PayCheck book?
The LifeTime PayCheck by Rick Kelly is available free at thelifetimepaycheck.com. It explains in plain language how to create guaranteed lifetime income from your own savings.
Is this the same as buying an annuity?
A guaranteed lifetime paycheck is typically created using certain types of annuities — but not all annuities are designed for lifetime income, and contracts vary widely in guarantees, costs, and spousal protection. That is why education comes first: understand the strategy before evaluating any product.
What does it mean that Rick Kelly is a safemoney.com verified advisor?
safemoney.com is a nationally recognized retirement education platform that vets and lists independent advisors held to strict education-first standards. Rick Kelly is verified on the platform, in addition to holding the Certified Senior Advisor (CSA) and Certified Annuity Specialist (CAS) credentials.
Will I lose access to my money?
Only the portion used to create the lifetime paycheck is committed to that job — and some contracts include liquidity provisions, which vary by product and should be reviewed carefully before any decision. The rest of your savings remains fully invested and accessible. The strategy is a division of labor, not a lock-up of everything you own.
Rick Kelly is a Certified Senior Advisor (CSA) and Certified Annuity Specialist (CAS), and a vetted safemoney.com advisor. He helps Self-Saved Retirees turn a lifetime of saving into income, principal protection, and peace of mind — with education first and no sales pressure.
Take the next step toward certainty
Get Rick Kelly's book The LifeTime PayCheck, book a free call, or reach out directly. No sales pressure — just clear, practical guidance.
Put this retirement planning idea into context
Compare Social Security claiming ages, then learn how dependable income and pension replacement planning may fit around the benefit you choose.